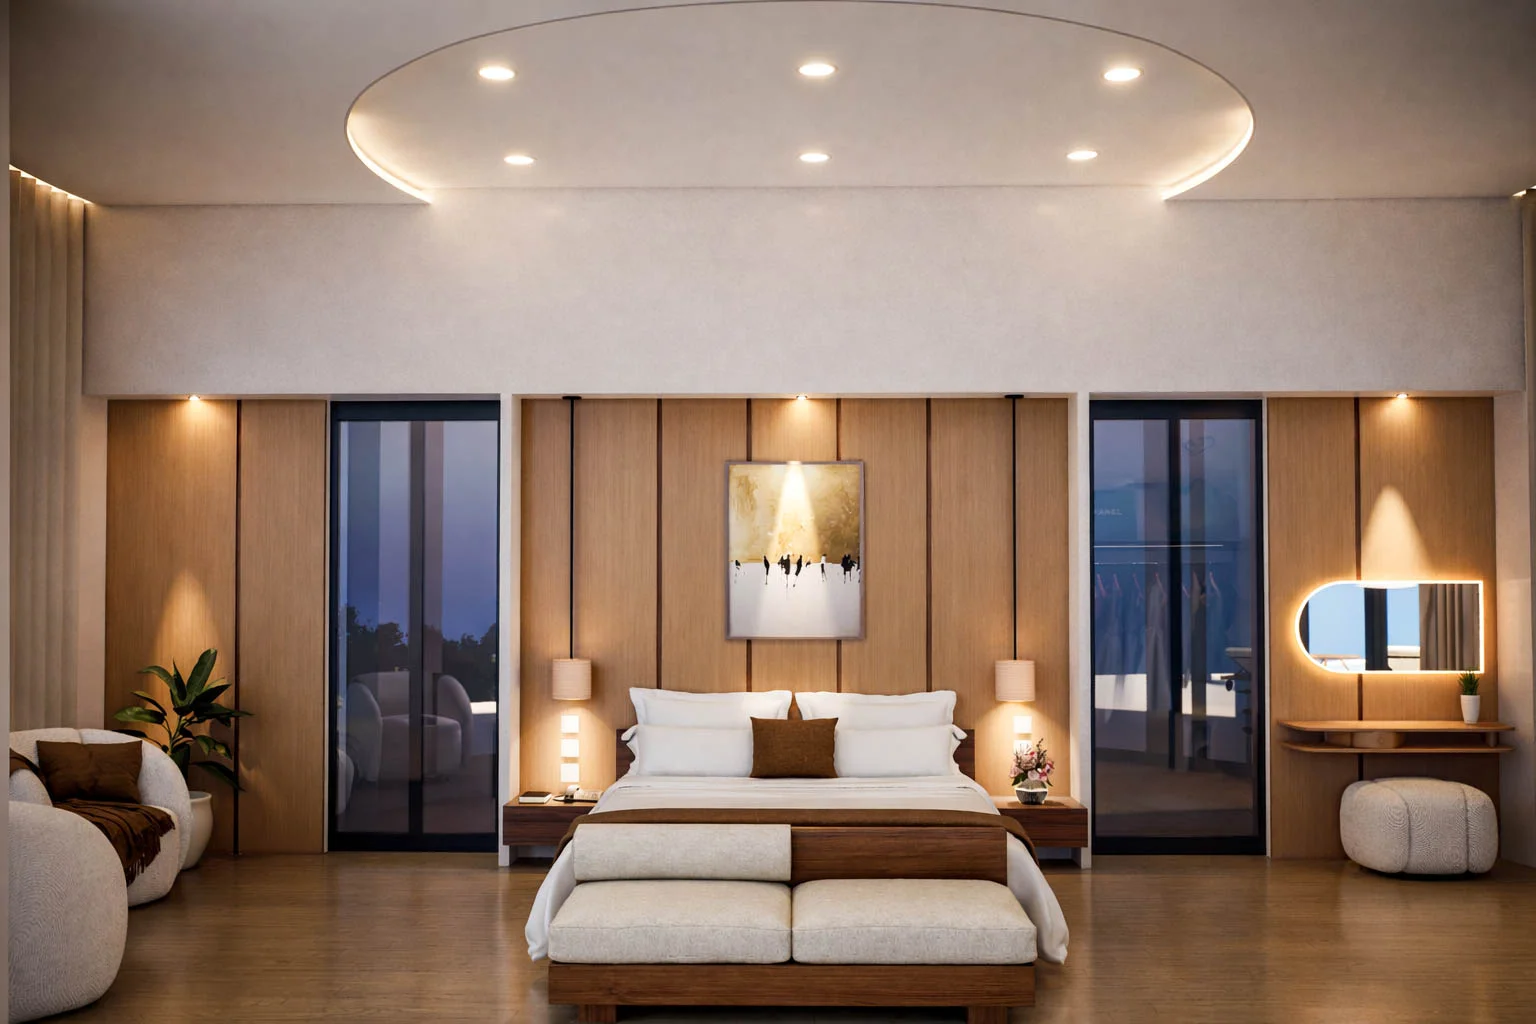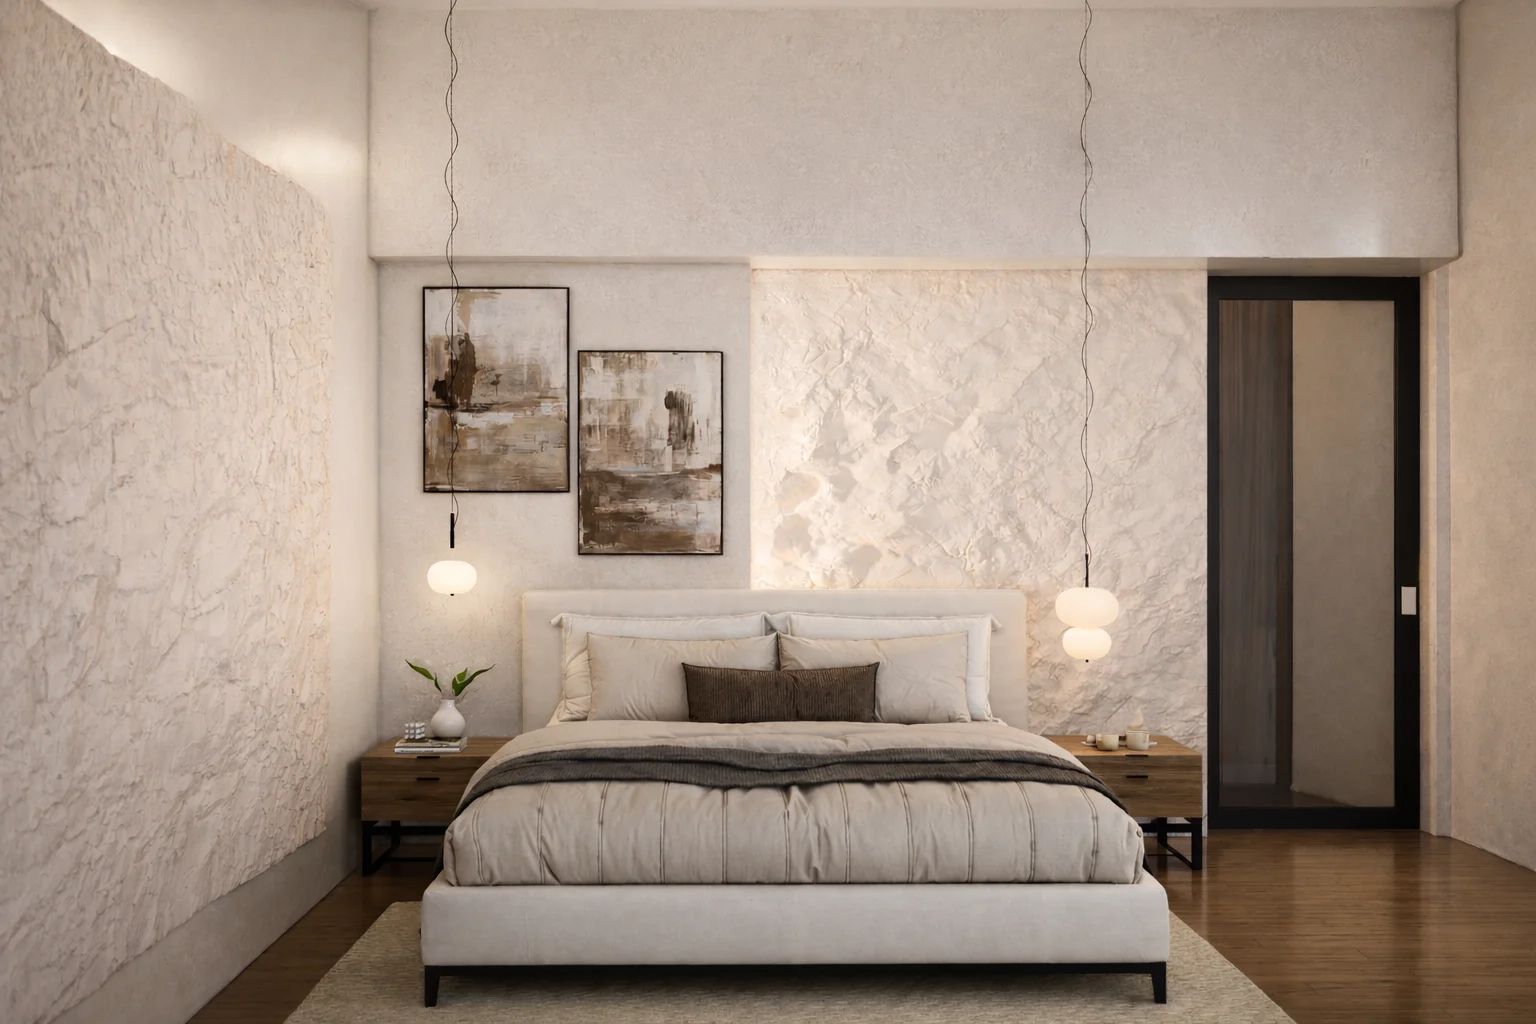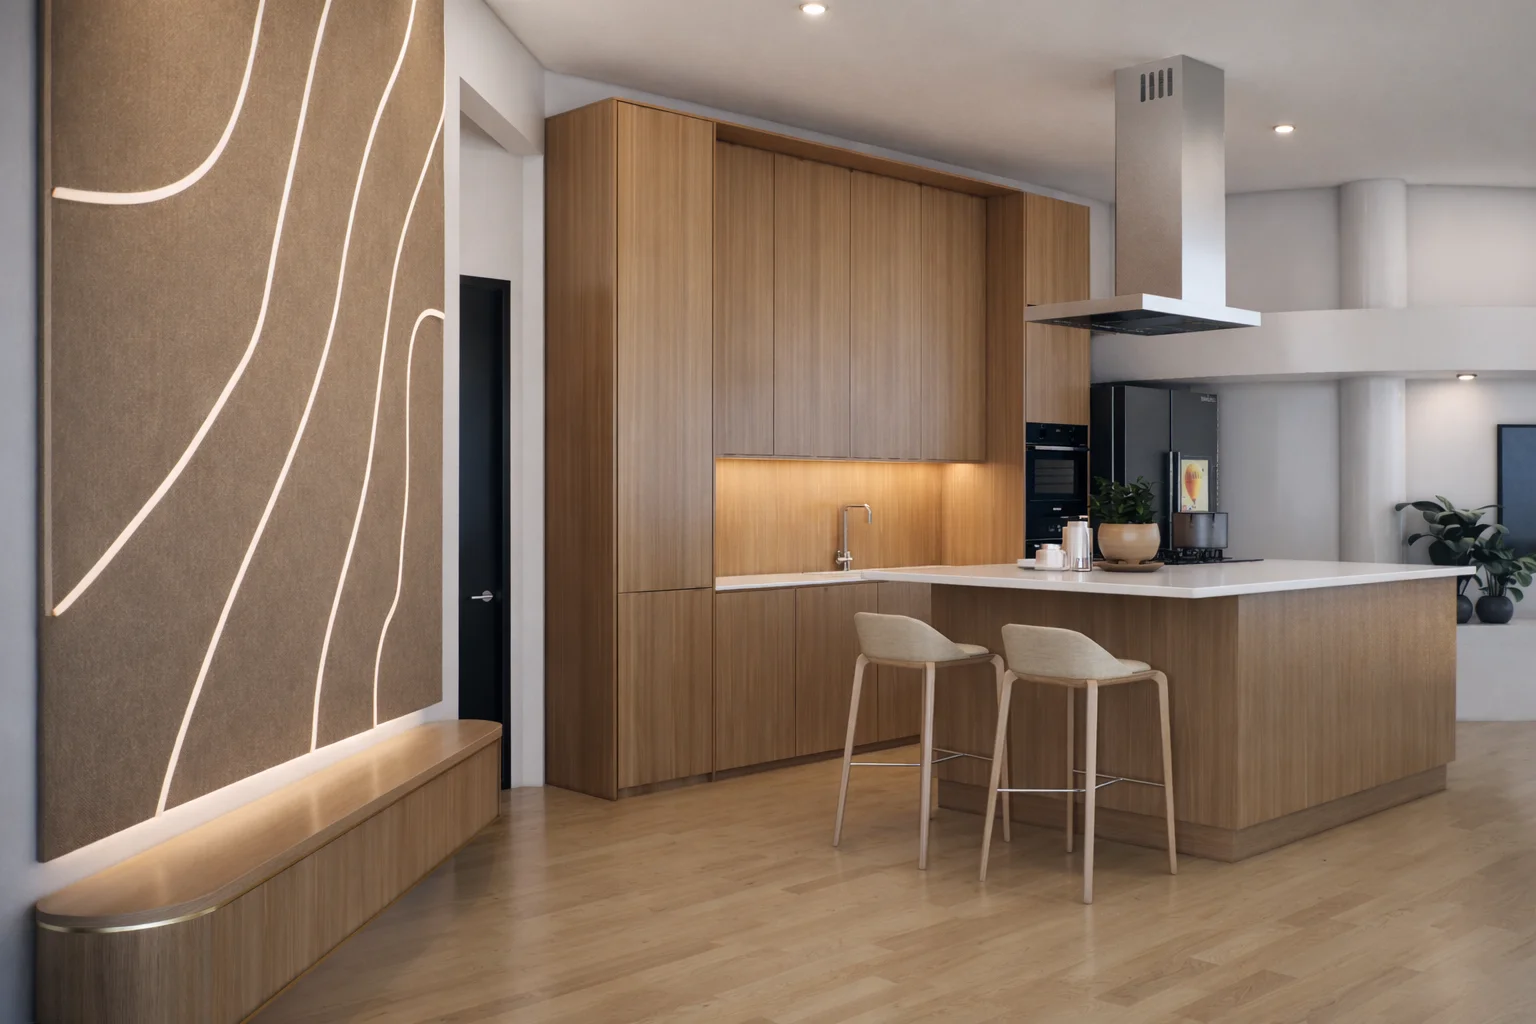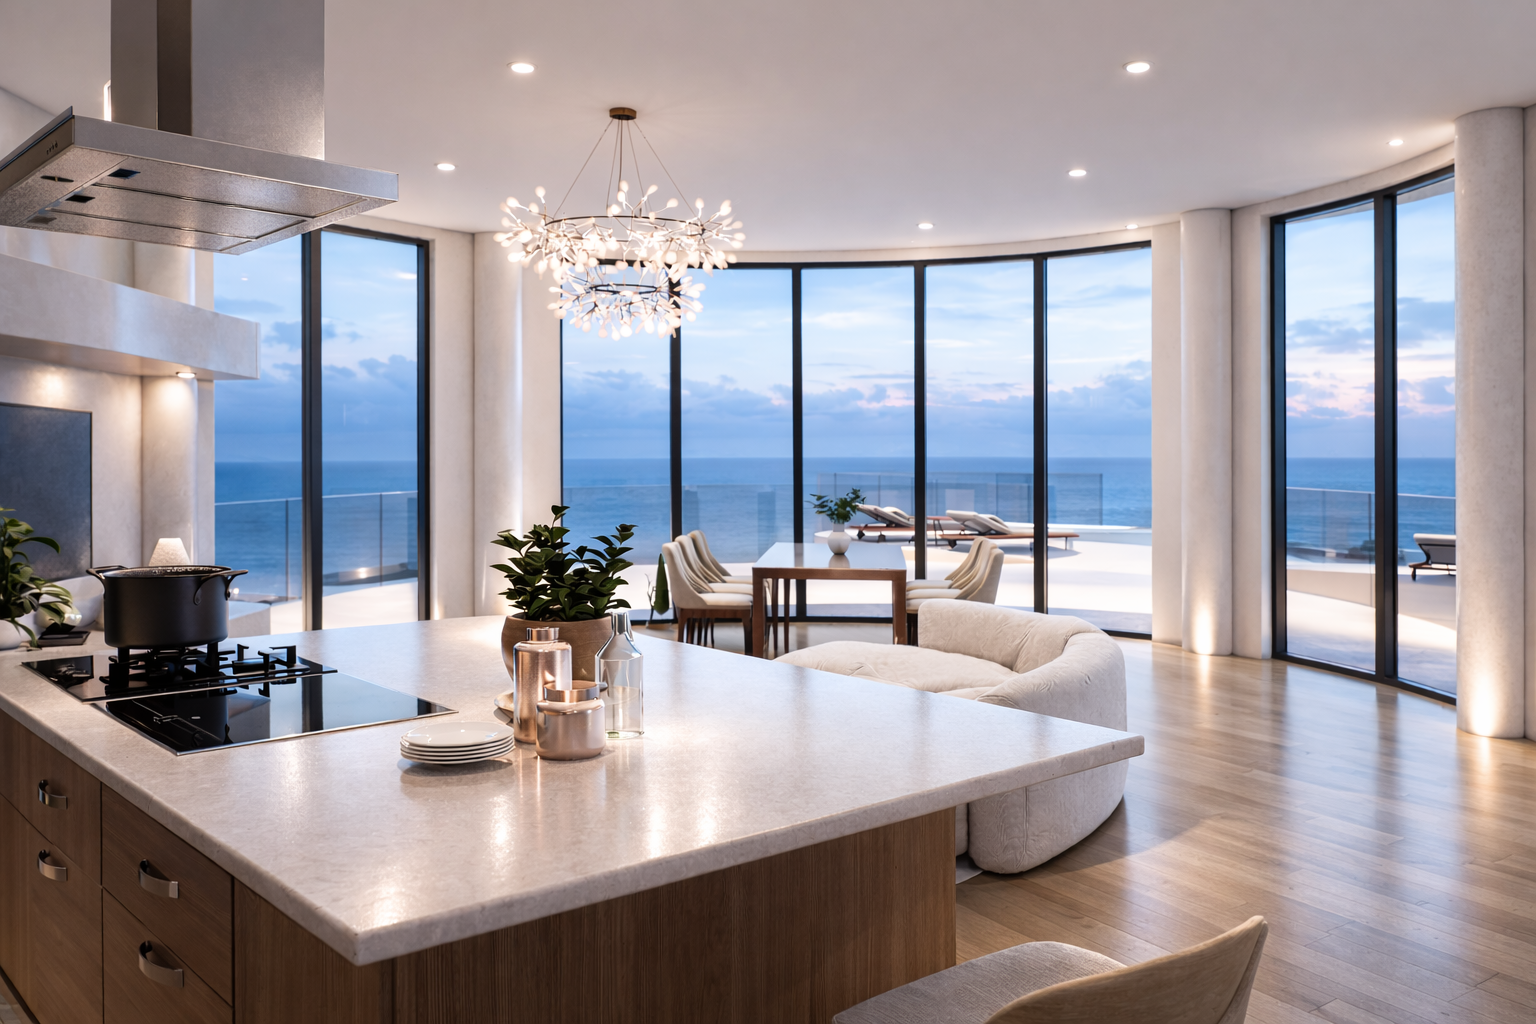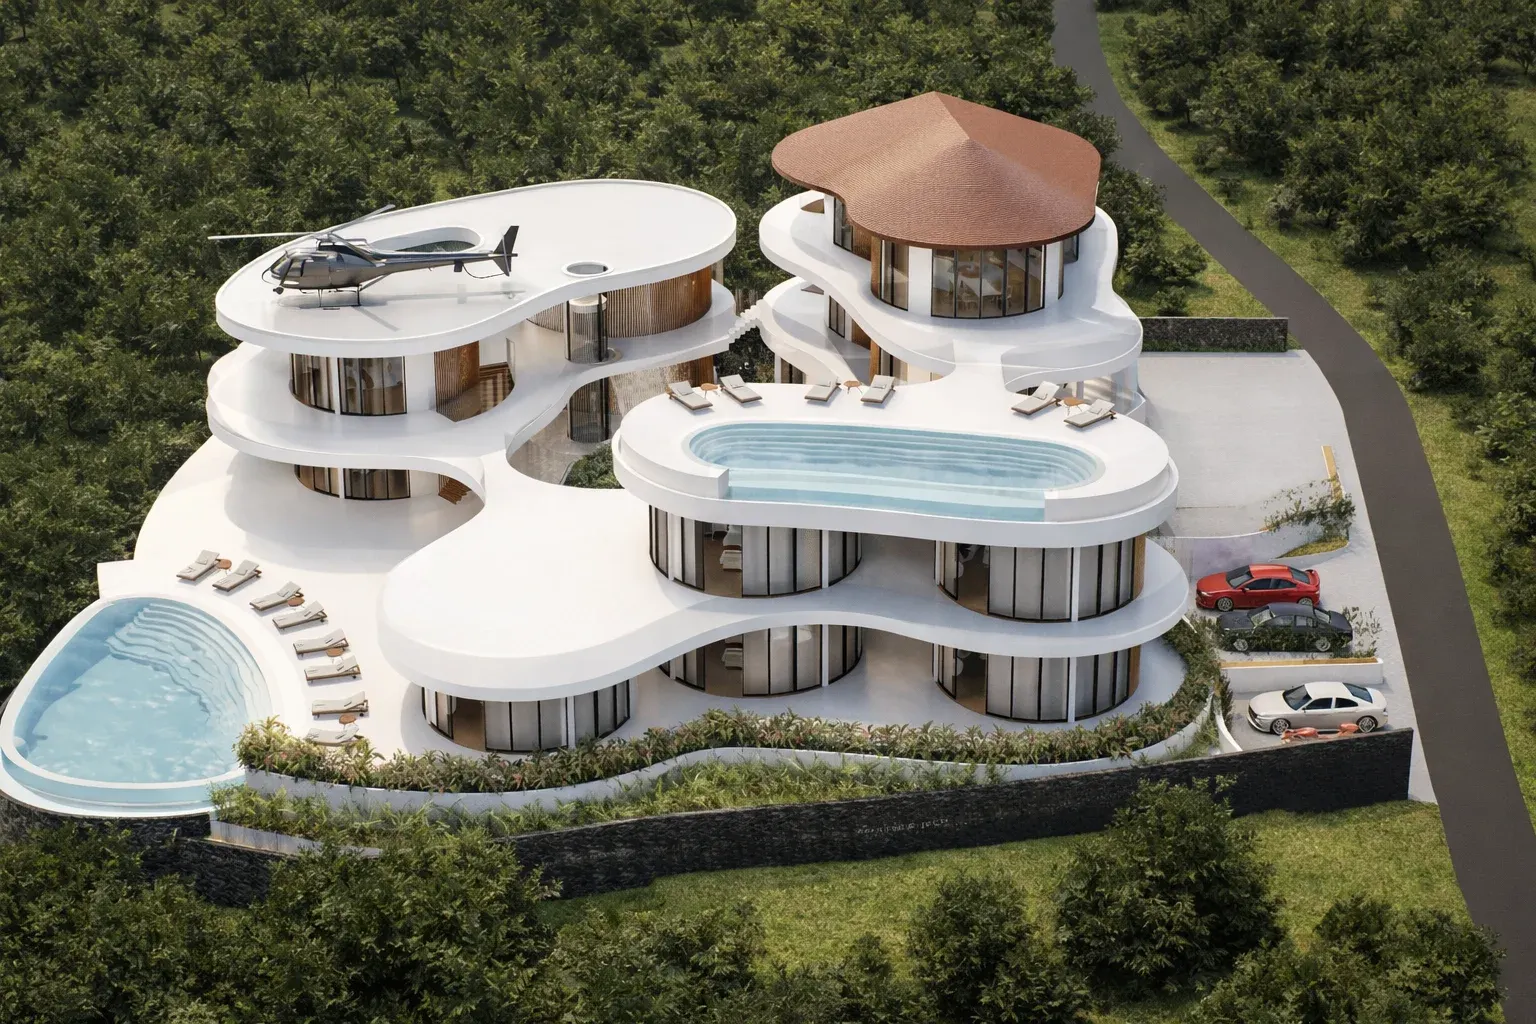
Domo Resort is a boutique eco-resort planned on the cliffs of Nusa Penida, the island east of Bali. The programme, confirmed by the owner, has 16 keys: 8 Ocean View Master Villas of about 50 m², 6 Standard Rooms of about 40 m² and 2 Penthouses of about 128 m², one of them with a private infinity pool. A reception and lounge, a bar and restaurant, a spa with sauna and a public pool complete the resort, for a gross floor area of about 3,636 m².
The architecture follows a curvilinear, contemporary tropical language with natural materials, a strong indoor–outdoor connection and low-impact construction. Site area, land title, sea access and permits are still being verified and are listed as open points on this page.
A 16-key boutique eco-resort on the cliffs of Nusa Penida: 8 Ocean View Master Villas, 6 Standard Rooms and 2 Penthouses, with restaurant, spa and infinity pool. Returns are shown in three scenarios from one financial model with explicit, sourced assumptions.
€3,475k
€50k
22.0%
Under legal verification
16 keys: 8 Ocean View Master Villas, 6 Standard Rooms and 2 Penthouses (one with a private pool). Published rates are peak-season rack rates; the model uses a lower realised rate.
The typology rates above are peak-season list prices. Revenue is calculated on a realised blended ADR of €250 (year 1, 2029 prices), i.e. 61% of the weighted rack rate, to reflect low-season pricing (5 months at 64% of the realised rate), packages and complimentary nights. Each typology's realised rate is derived from its rack rate in the same proportion. The realisation factor is an assumption to be validated with a revenue-management study.
ADR figures are net of the 10% regional hotel tax (PB1) and of the service charge. OTA commissions and payment fees are treated as distribution costs in OPEX, not deducted from ADR.
Ancillary revenue is built from operating drivers, not as a flat share of room revenue. Base case, year 3 (72% occupancy, 4.205 room nights, 7.569 guest nights):
| Stream | Volume | Avg. price | Revenue | Cost of sales | Margin |
|---|---|---|---|---|---|
| Restaurant & bar | 4.541 covers | €27 | €145.939 | 35% | €94.860 |
| Spa & wellness | 2.649 treatments | €21 | €56.754 | 25% | €42.566 |
| Activities & transfers | 4.205 room nights | €11 | €45.043 | 40% | €27.026 |
| Events | 12 events | €1,607 | €19.282 | 40% | €11.569 |
| Total ancillary | €267.018 | 23.7% of room revenue | |||
F&B: 60% of guest nights at €25 per cover, plus 20% external guests. Spa: 35% capture at €20. Activities: €10 per room night (transfer, tour and rental commissions). Events: 1 per month at €1,500. Conservative and upside scenarios use lower and higher capture and spend.
Nusa Penida attracts diving, nature and photography travellers and receives spillover demand from Bali. The island is a niche premium destination rather than a mass market: the opportunity lies in a small, design-led property with a realised rate above the island's short-stay average.
Schedule anchored on the funding deadline (Feb 2027): design from Oct 2026, construction 18 months from Aug 2027, opening Apr 2029. Any change to the opening date moves the pre-opening programme with it.
Achieving the targeted 65% occupancy in operating year 2 depends on a structured pre-opening sales and marketing programme beginning at least six months before the resort welcomes its first guests. This programme will build awareness, qualified demand, distribution partnerships and advance bookings. The occupancy figure is a planning target, not a guaranteed result, and will be reviewed against measurable booking and conversion milestones.
With the opening planned for Apr 2029, the programme starts no later than Oct 2028 (brand foundations from Apr 2028). If the opening date changes, this milestone moves with it.
| Brand identity, website and booking engine | €15.000 |
| Content: renders, photography, video, storytelling | €15.000 |
| PR, travel trade and concierge partnerships, familiarisation trips | €12.000 |
| Measurable campaigns (search, social, email) and advance-booking offers | €20.000 |
| CRM, guest database with consent, analytics | €5.000 |
| Sales & marketing lead (part-time, 6 months) | €8.000 |
| Proposed budget | €75.000 |
Proposed pre-opening budget of €75.000, included in CAPEX as a separate line and pending approval. Recurring marketing (3% of revenue) and OTA commissions are in OPEX.
Sponsor / GP: brand, budget, approvals and partnerships. Sales & marketing lead: execution, distribution set-up and reporting. Revenue manager (or operator): pricing, channel mix and OTA connectivity. Studio: architectural content and visuals. External PR agency: media and trade relations.
An optional Unreal Engine 5 experience could bring the resort to life before opening. Guests and future visitors would be able to explore a high-quality interactive version of the property, discover its architecture and take part in shareable experiences. This offers a way to build an engaged community beyond conventional photography and video. Development would proceed in stages, subject to a separate budget and measurable marketing goals; no revenue from this initiative is included in the base financial forecast.
Renders and film show the resort; an interactive scene lets people walk the cliff path at sunset, open a villa, compare the two penthouses and share a moment with friends. It gives future guests a reason to return while the site is still under construction, and it turns interest into contacts that the pre-opening programme can follow up.
Terrain, landscape and the resort massing from the architectural model; one villa and the penthouse interiors; a guided walk. Goal: validate quality, performance and interest with a small test group.
Small shareable challenges (sunset photo spots, cliff-path trails, discover-the-villas), a visitor profile and an opt-in to receive opening offers. Goal: measured usage, share rate and qualified contacts feeding the pre-opening database.
Seasonal events, more of the island, multiplayer moments. Decided after phase 2 on measured usage, conversion to bookings and cost per contact.
A downloadable PC/Mac build, interactive pixel streaming from the cloud and browser access have different costs, quality and reach. Unreal Engine 5 has no native browser export, so browser access means streaming (per-session cost) or a reduced web version. The platform is chosen after the phase-1 prototype, not promised beforehand.
Community data is collected with explicit consent, a clear purpose (opening offers and updates), an easy opt-out and compliance with Indonesian personal-data law (UU PDP) and the GDPR for European guests.
A complete experience needs its own design, development, distribution platform, maintenance and budget. Costs, player numbers and any economic return are not estimated here and are not included in CAPEX, revenue or IRR until an approved quotation and measurable objectives exist.
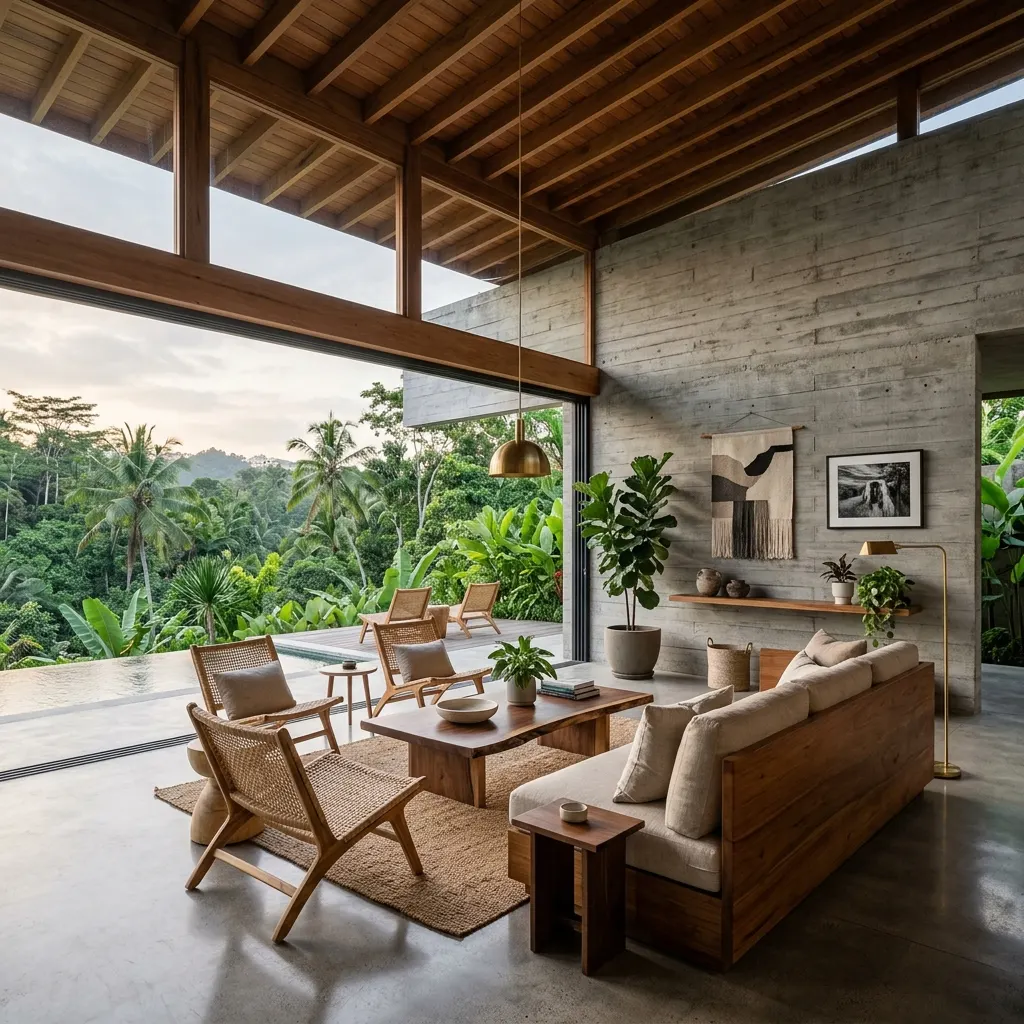
Area data (island listings, Bali hotel occupancy) describe the market; the resort's own rate and occupancy are planning targets for a new, design-led property and are not derived from a documented comparable set. A comparable study is pending.
| Metric | Value |
|---|---|
| Land Acquisition | €350.000 |
| Construction | €1.500.000 |
| Furniture & Interiors | €650.000 |
| Other | €315.000 |
| Design & Architecture | €250.000 |
| Project Management | €70.000 |
| Permits & Legal | €75.000 |
| Pre-opening | €75.000 |
| Working capital | €190.000 |
| Total Investment | €3.475.000 |
| Exit value (gross, year 5) | €8.315.658 |
| Net exit proceeds after 3.0% selling costs and 2.5% transfer tax | €7.858.297 |
| Base-case IRR | 22.0% |
| Equity multiple | 3.00x |
| Timeline | 30 Months |
The investment case rests on three elements: a low-density property that is easy to fill (16 keys), a rate positioned above the island average thanks to design and location, and a cost base sized for a small team. Every figure is derived from the model shown on this page and can be reviewed line by line.
Domo Resort is a 16-key boutique property on a cliffside site of Nusa Penida with ocean views. The architecture and the size of the inventory are the basis for a realised rate above the island's short-stay average; the target rate and occupancy are planning assumptions and are tested in three scenarios.
The resort is sized for a team of 26 with lean overheads. Operating costs are built line by line (payroll with on-costs, cost of sales, distribution, marketing, utilities, maintenance and FF&E reserve, insurance, administration and a management fee) so that the EBITDA margin follows from the cost structure rather than from a target.
Nusa Penida has grown from a day-trip destination into a multi-day one, with demand driven by diving, nature and photography and by spillover from Bali. Official visitor statistics, a comparable-rate study and the permitting framework are still to be documented; the model does not rely on visitor-growth assumptions and treats regulatory risk (development moratoria, tourist levies) as a timeline risk.
Simulate your returns by adjusting the investment amount below.
22.0%
€1.6M
48.2%
5 Years
Year 5 (with exit)
€3.5M
€15.724
Pro-rata share of base-case free cash flow, before any sponsor promote or platform fee. IRR (22.0%) is a rate of return over the whole holding period including the exit; it is not an annual income.Figures are pro-rata shares of the base-case model, before any promote or fee. Actual performance may vary. The three scenarios run through the same model with different occupancy, ADR, ancillary, cost, capital-cost and timing assumptions. The conservative case is a downside stress: lower rates and occupancy, a third-party operator fee, a 10% construction overrun and a six-month opening delay together.
The resort is planned as a low-density boutique property: 16 keys across three typologies, a restaurant and bar, a spa and a public infinity pool. Revenue comes from a realised rate positioned above the island's short-stay average and from ancillary services sized on guest nights.
Operating costs are built line by line: payroll for 26 staff with on-costs, cost of sales, distribution and marketing, utilities, maintenance and an FF&E reserve, insurance, administration and a management fee. All ratios are listed in the assumptions table below.
>Nusa Penida is one of Bali’s fastest-growing destinations, with increasing demand for high-end, design-driven accommodations.
Area data (island listings, Bali hotel occupancy) describe the market; the resort's own rate and occupancy are planning targets for a new, design-led property and are not derived from a documented comparable set. A comparable study is pending.
The base case targets an EBITDA margin of 48% at stabilisation (year 5). Cash available for distribution is EBITDA after corporate income tax; the model assumes 100% equity funding and no debt.
Returns are presented in three scenarios with the same formulas; the sensitivity table and the delay/overrun variants show how much the outcome depends on rate, occupancy, timing and construction cost.
Reducing operational complexity and staff overhead.
Architectural identity supporting premium ADR.
Accommodation, F&B, and Wellness revenue streams.
Direct sponsor involvement in development & control.
Disclaimer: This material is for informational purposes only and does not constitute an offer or solicitation to invest. Details are provided upon request for qualified partners.
This chart shows how the €3.475.000 total capital requirement is allocated: the admin budget of €3.210.000, the proposed pre-opening programme and a working-capital reserve equal to 3 months of operating costs.
| Category | Investment Item | Status | Amount |
|---|---|---|---|
| Land Acquisition | Land acquisition | Title pending | €350.000 |
| Construction | Main Structure & Roof | Budget line | €1.500.000 |
| Furniture & Interiors | Elite FF&E Package | Budget line | €450.000 |
| Other | Safety Reserve | Contingency | €290.000 |
| Design & Architecture | Architectural & Technical Design | Budget line | €200.000 |
| Furniture & Interiors | Lighting & decoration | Budget line | €80.000 |
| Furniture & Interiors | Equipment (AC, system) | Budget line | €120.000 |
| Project Management | Project management | Budget line | €70.000 |
| Design & Architecture | Engineering consultant | Budget line | €50.000 |
| Permits & Legal | Building permits & licenses | Budget line | €60.000 |
| Permits & Legal | Legal & company setup | Budget line | €15.000 |
| Other | Staff training & hiring | Budget line | €25.000 |
| Pre-opening | Pre-opening sales & marketing programme | Proposed | €75.000 |
| Working capital | Working capital & opening cash reserve | Formula | €190.000 |
| Total capital requirement | €3.475.000 | ||
These items are not itemised in the current budget. Either they are included in the 'Main Structure & Roof' lump sum, which must be confirmed with the contractor, or they will add to the total. The total above is therefore a floor, not a ceiling.
Operating cost build-up (base case, year 3) · Revenue €1.393.090
| Cost line | Basis | Amount | % of revenue |
|---|---|---|---|
| Payroll | 26 staff, €158.880 base payroll + 30% on-costs (BPJS, THR, meals, uniforms, training) | €217.000 | 15.6% |
| Cost of sales | F&B 35%, spa 25%, activities and events 40% of the respective revenue | €90.997 | 6.5% |
| Distribution (OTA & payments) | 50% of room nights via OTA at 15% commission + 1.5% payment fees | €101.346 | 7.3% |
| Sales & marketing (recurring) | 3% of total revenue | €41.793 | 3.0% |
| Utilities (power, generator, water) | €24.000 fixed + 2% of revenue | €53.077 | 3.8% |
| Repairs & maintenance | €2.800 per key | €47.068 | 3.4% |
| FF&E reserve | 3% of total revenue | €41.793 | 3.0% |
| Insurance | €8.000 | €8.405 | 0.6% |
| Administration, licences, technology | accounting & licences €10.000, admin & logistics €15.000, PMS/booking systems €9.000 | €35.721 | 2.6% |
| Housekeeping consumables & laundry | €8 per room night | €35.341 | 2.5% |
| Management fee | 5% of total revenue | €69.654 | 5.0% |
| Total operating costs | of which fixed €333.410 | €742.196 | 53.3% |
| EBITDA | €650.893 | 46.7% |
The staff table and cost items entered in the admin are the documented cost base (€325.880 per year: €158.880 payroll and €167.000 other items). The build-up above adds on-costs and the variable costs that scale with revenue, which is why total operating costs are higher than the admin list.
| Conservative | Base | Upside | |
|---|---|---|---|
| Occupancy ramp (Y1 → stabilised) | 45% → 55% → 62% → 65% | 55% → 65% → 72% → 75% | 60% → 72% → 78% → 80% |
| Realised ADR (year 1) | €225 | €250 | €280 |
| Ancillary (% of rooms) | 18.4% | 23.6% | 30.9% |
| Management fee (% of revenue) | 12% | 5% | 5% |
| Construction overrun | 10% | 0% | 0% |
| Opening delay | 6 months (Oct 2029) | 0 months (Apr 2029) | 0 months (Apr 2029) |
| Exit cap rate | 10.0% | 9.0% | 8.5% |
| Total capital | €3.740.000 | €3.475.000 | €3.501.000 |
| Year-5 revenue | €1.160.184 | €1.553.631 | €1.964.819 |
| Year-5 EBITDA | €345.781 (30%) | €748.409 (48%) | €1.049.047 (53%) |
| Gross exit value | €3.457.812 | €8.315.658 | €12.341.725 |
| Net exit proceeds | €3.267.633 | €7.858.297 | €11.662.930 |
| Project IRR | 2.9% | 22.0% | 30.8% |
| Equity multiple | 1.18x | 3.00x | 4.37x |
| Payback from operations | > 10 years | 6.4 Years | 4.8 Years |
| Avg. cash yield on capital | 6.2% | 14.8% | 20.7% |
| Variant | Total capital | Opening | IRR | Change vs base |
|---|---|---|---|---|
| Base | €3.475.000 | Apr 2029 | 22.0% | — |
| Base + 6-month delay | €3.523.000 | Oct 2029 | 20.8% | -1.2 pt |
| Base + 12-month delay | €3.571.000 | Apr 2030 | 19.6% | -2.4 pt |
| Base + 10% construction overrun | €3.690.000 | Apr 2029 | 20.7% | -1.3 pt |
| Base + 20% construction overrun | €3.905.000 | Apr 2029 | 19.5% | -2.5 pt |
| Base + 6-month delay + 10% overrun | €3.738.000 | Oct 2029 | 19.5% | -2.5 pt |
A delay adds holding costs (€8.000 per month) and postpones every operating cash flow; an overrun is applied to the construction and fit-out lines.
| Typology | Units | Peak ADR | Low ADR | Room nights | Room revenue |
|---|---|---|---|---|---|
| Ocean View Master Villa | 8 | €375 | €188 | 2.103 | €616.126 |
| Standard Room | 6 | €150 | €75 | 1.577 | €184.831 |
| Penthouse | 1 | €583 | €292 | 263 | €119.800 |
| Penthouse with Private Pool | 1 | €1,000 | €500 | 263 | €205.371 |
| Total | 16 | Peak season €829.942 / Low season €296.130 | 4.205 | €1.126.072 | |
7 peak months at 128% and 5 low months at 64% of the realised rate; occupancy applied uniformly. Split shown for planning; the annual total equals keys × occupancy × realised ADR × 365.
Operating assumptions of the base case; the scenario buttons switch every figure on this page.
Total gross income generated over the project lifecycle.
Net capital remaining after all costs and investment recovery.
Performance operative excluding non-cash items and taxes.
Net profit share attributable to your specific investment.
Cumulative free cash flow from the first capital call, with the net exit proceeds in the exit year. This is a projection, not a guarantee.
| Year | Estimated Occupancy | Gross Revenue | Operational Profit (EBITDA) | Corporate tax | Free cash flow |
|---|---|---|---|---|---|
| Year 1 | 55% | €997.660 | €386.064 | €46.214 | €339.850 |
| Year 2 | 65% | €1.216.932 | €533.830 | €78.723 | €455.108 |
| Year 3 | 72% | €1.393.090 | €650.893 | €104.477 | €546.417 |
| Year 4 | 75% | €1.501.093 | €719.434 | €119.556 | €599.879 |
| Year 5 | 75% | €1.553.631 | €748.409 | €125.930 | €622.479 |
| Year 6 | 75% | €1.608.008 | €778.493 | €132.549 | €645.945 |
| Year 7 | 75% | €1.664.289 | €809.727 | €139.420 | €670.307 |
| Year 8 | 75% | €1.722.539 | €842.154 | €146.554 | €695.600 |
| Year 9 | 75% | €1.782.828 | €875.819 | €171.835 | €703.983 |
| Year 10 | 75% | €1.845.227 | €910.766 | €179.523 | €731.242 |
Annual figures for operating years 1–10 (base case). Year 1 starts at the opening (Apr 2029). Free cash flow = EBITDA − corporate income tax; the FF&E reserve is already inside operating costs.
+3.50% Annual
+2.50% Annual
23.9% operating costs only
44.5% incl. 8% preferred return
Occupancy at which year-3 revenue covers all operating costs (first figure), or operating costs plus an 8% annual return on the total capital (second figure). Neither covers capital repayment or debt, which the model does not assume.
| ADR \ OCC | 60% | 65% | 70% | 75% | 80% |
|---|---|---|---|---|---|
| €200 | 7.8% | 10.7% | 13.2% | 15.5% | 17.7% |
| €225 | 11.5% | 14.3% | 16.7% | 19.0% | 21.1% |
| €250 | 14.7% | 17.4% | 19.8% | 22.0% | 24.1% |
| €275 | 17.6% | 20.2% | 22.6% | 24.8% | 26.8% |
| €300 | 20.2% | 22.8% | 25.1% | 27.3% | 29.3% |
Project IRR from the first capital call, including the year-5 exit at the scenario cap rate. Occupancy columns are the stabilised level; the ramp-up is scaled proportionally.
Legal Disclaimer: This sensitivity analysis is based on historical market performance and projected operational standards in Nusa Penida. Actual results may vary depending on global tourism trends, local regulations, and macroeconomic factors. This is not a guarantee of future returns.
| Assumption | Value | Source |
|---|---|---|
| Inventory | 16 keys (8 + 6 + 2) | Owner-confirmed unit programme; project brochure p. 2 |
| Rack rates by typology | Ocean View Master Villa €450, Standard Room €180, Penthouse €700, Penthouse with Private Pool €1,200 | Admin unit table (owner input) |
| Realised blended ADR used in the model | €250 (61%) | Owner input (admin ADR base); consistent with the €320 peak / €160 low seasonal split entered by the owner. Realisation vs rack rate to be validated. |
| ADR growth | +3.5% / Year | Owner input (admin) |
| Occupancy ramp | 55% → 65% → 72% → 75% | Planning target; Bali star-hotel occupancy around 60% (brochure p. 3). Requires the pre-opening programme. |
| Ancillary drivers | 23.6% of room revenue | Owner's service configuration (restaurant, spa, events); activities commission is a model assumption |
| Staffing | 26 staff, €158.880 per year | Admin staff table (owner input); on-costs 30% are a model assumption |
| Variable cost ratios | OTA 50% × 15%, Sales & marketing (recurring) 3%, FF&E 3%, Management fee 5% | Hospitality benchmarks (model assumption) |
| Fixed cost items | €101.800 / Year | Admin OPEX items (owner input): utilities €24.000, maintenance €2.800 per key, insurance €8.000, accounting €10.000, admin €15.000 |
| Corporate income tax | 22% | Indonesian statutory rate; PT PMA structure and any final-tax regime to be confirmed |
| Depreciation | buildings 20 years, FF&E 8 years | Model assumption for tax purposes |
| Development budget | €3.210.000 | Admin budget table (owner input, 12 lines) |
| Working capital | €190.000 = 3 months of operating costs | Model formula |
| Pre-opening sales & marketing programme | €75.000 | Proposal, pending approval |
| Exit | year 5, cap rate 9.0%, selling costs 3.0%, transfer tax 2.5% | Cap rate range stated by the owner (9–10%); selling costs and the 2.5% final transfer tax are model assumptions to be confirmed by counsel |
| Timeline | design 4 m, permits 6 m, construction 18 m, pre-opening 2 m → Apr 2029 | Admin durations; start re-based to the funding deadline; 18-month construction as stated on the page |
| Financing | 100% equity, no debt | No financing terms on record |
Download the full technical and financial overview of the project.
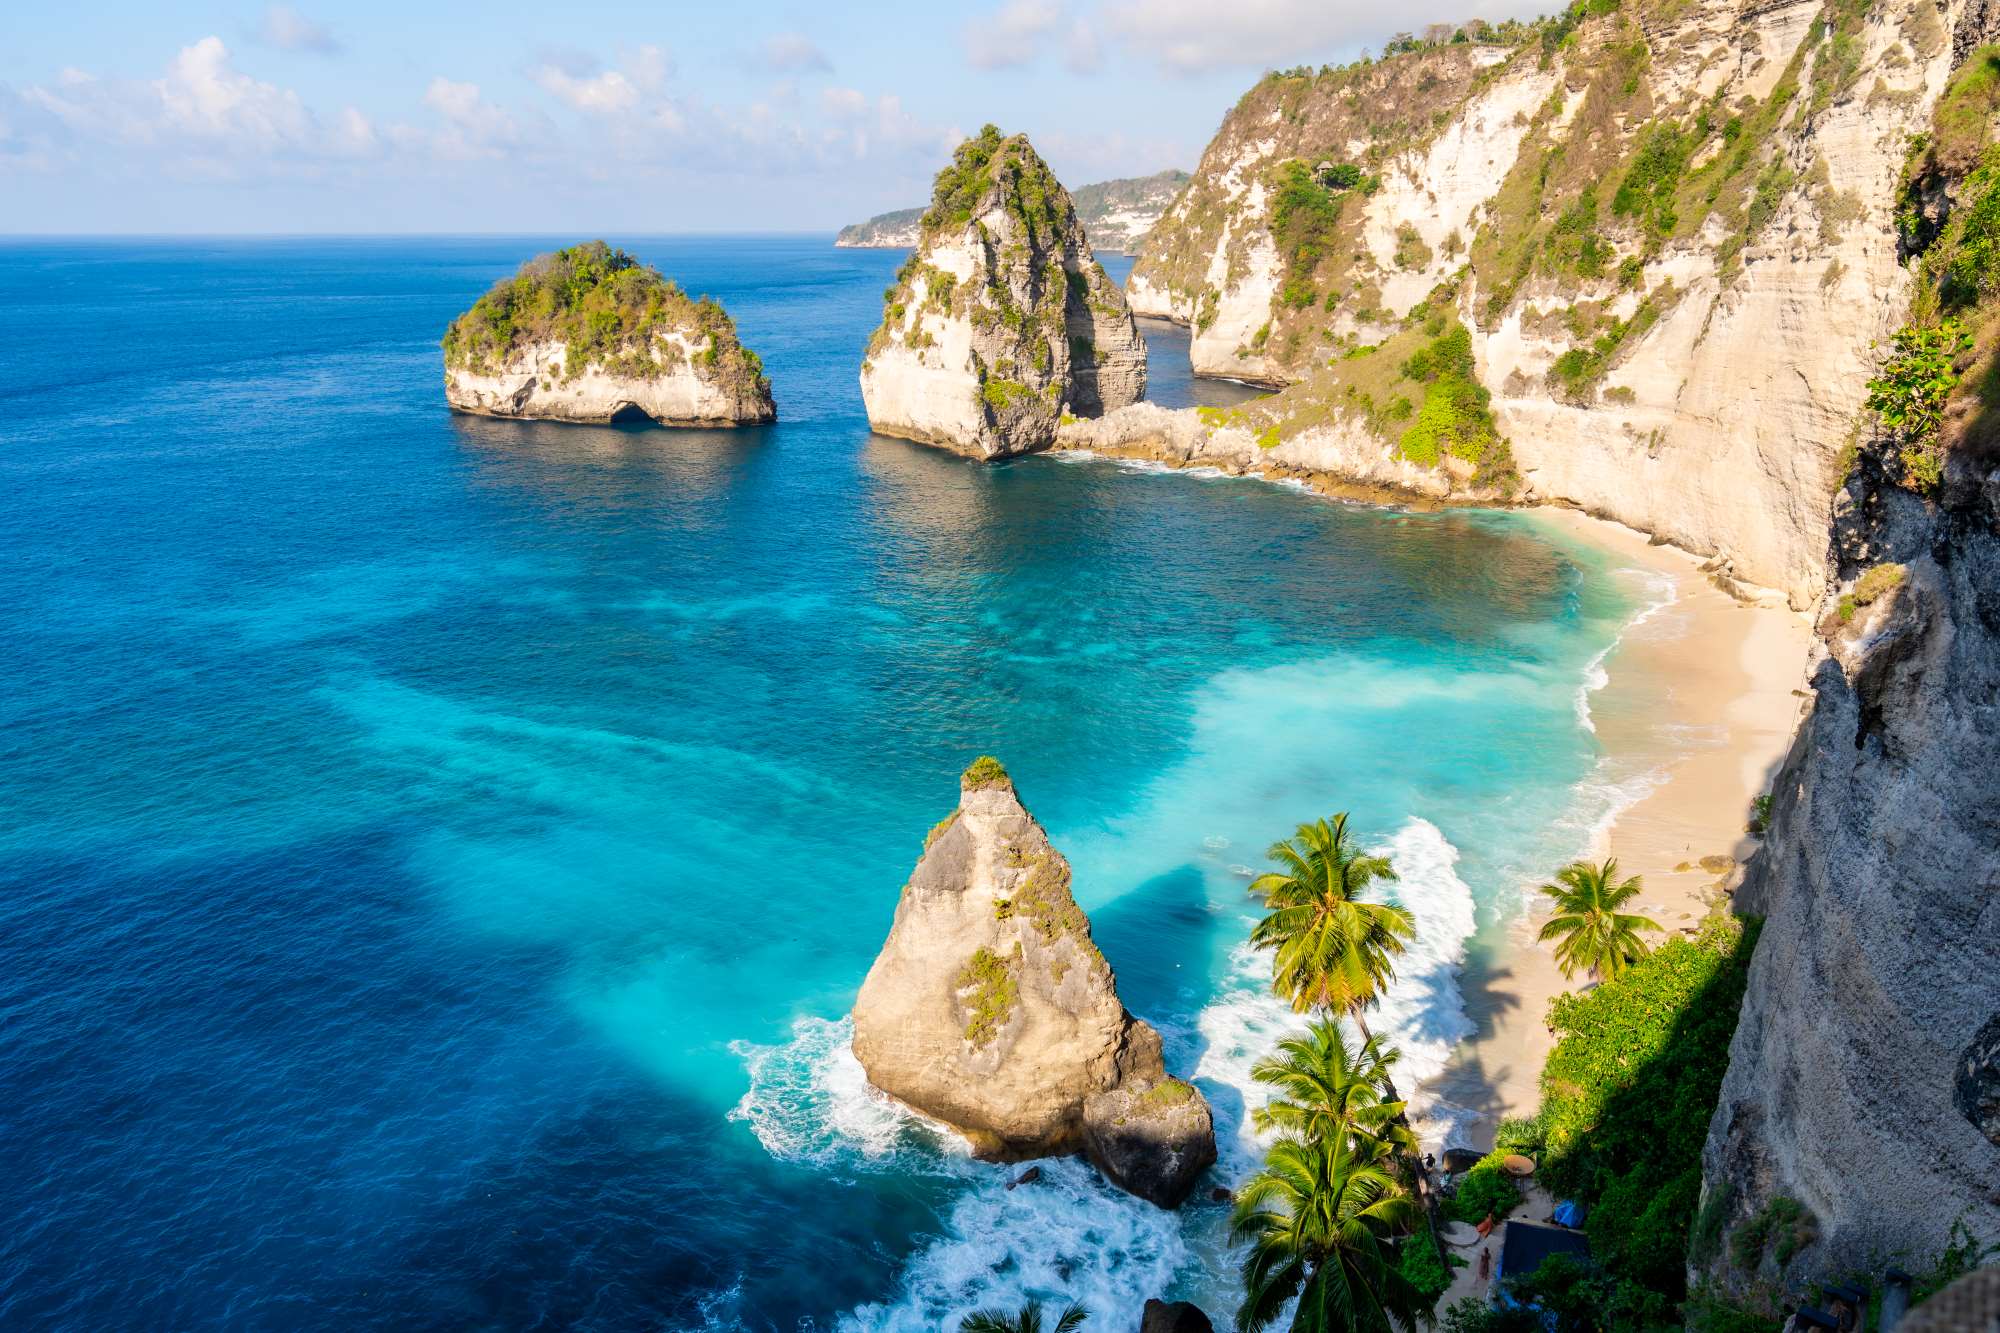
Unbelievable cliffside white sand beach on the eastern tip of Nusa Penida.
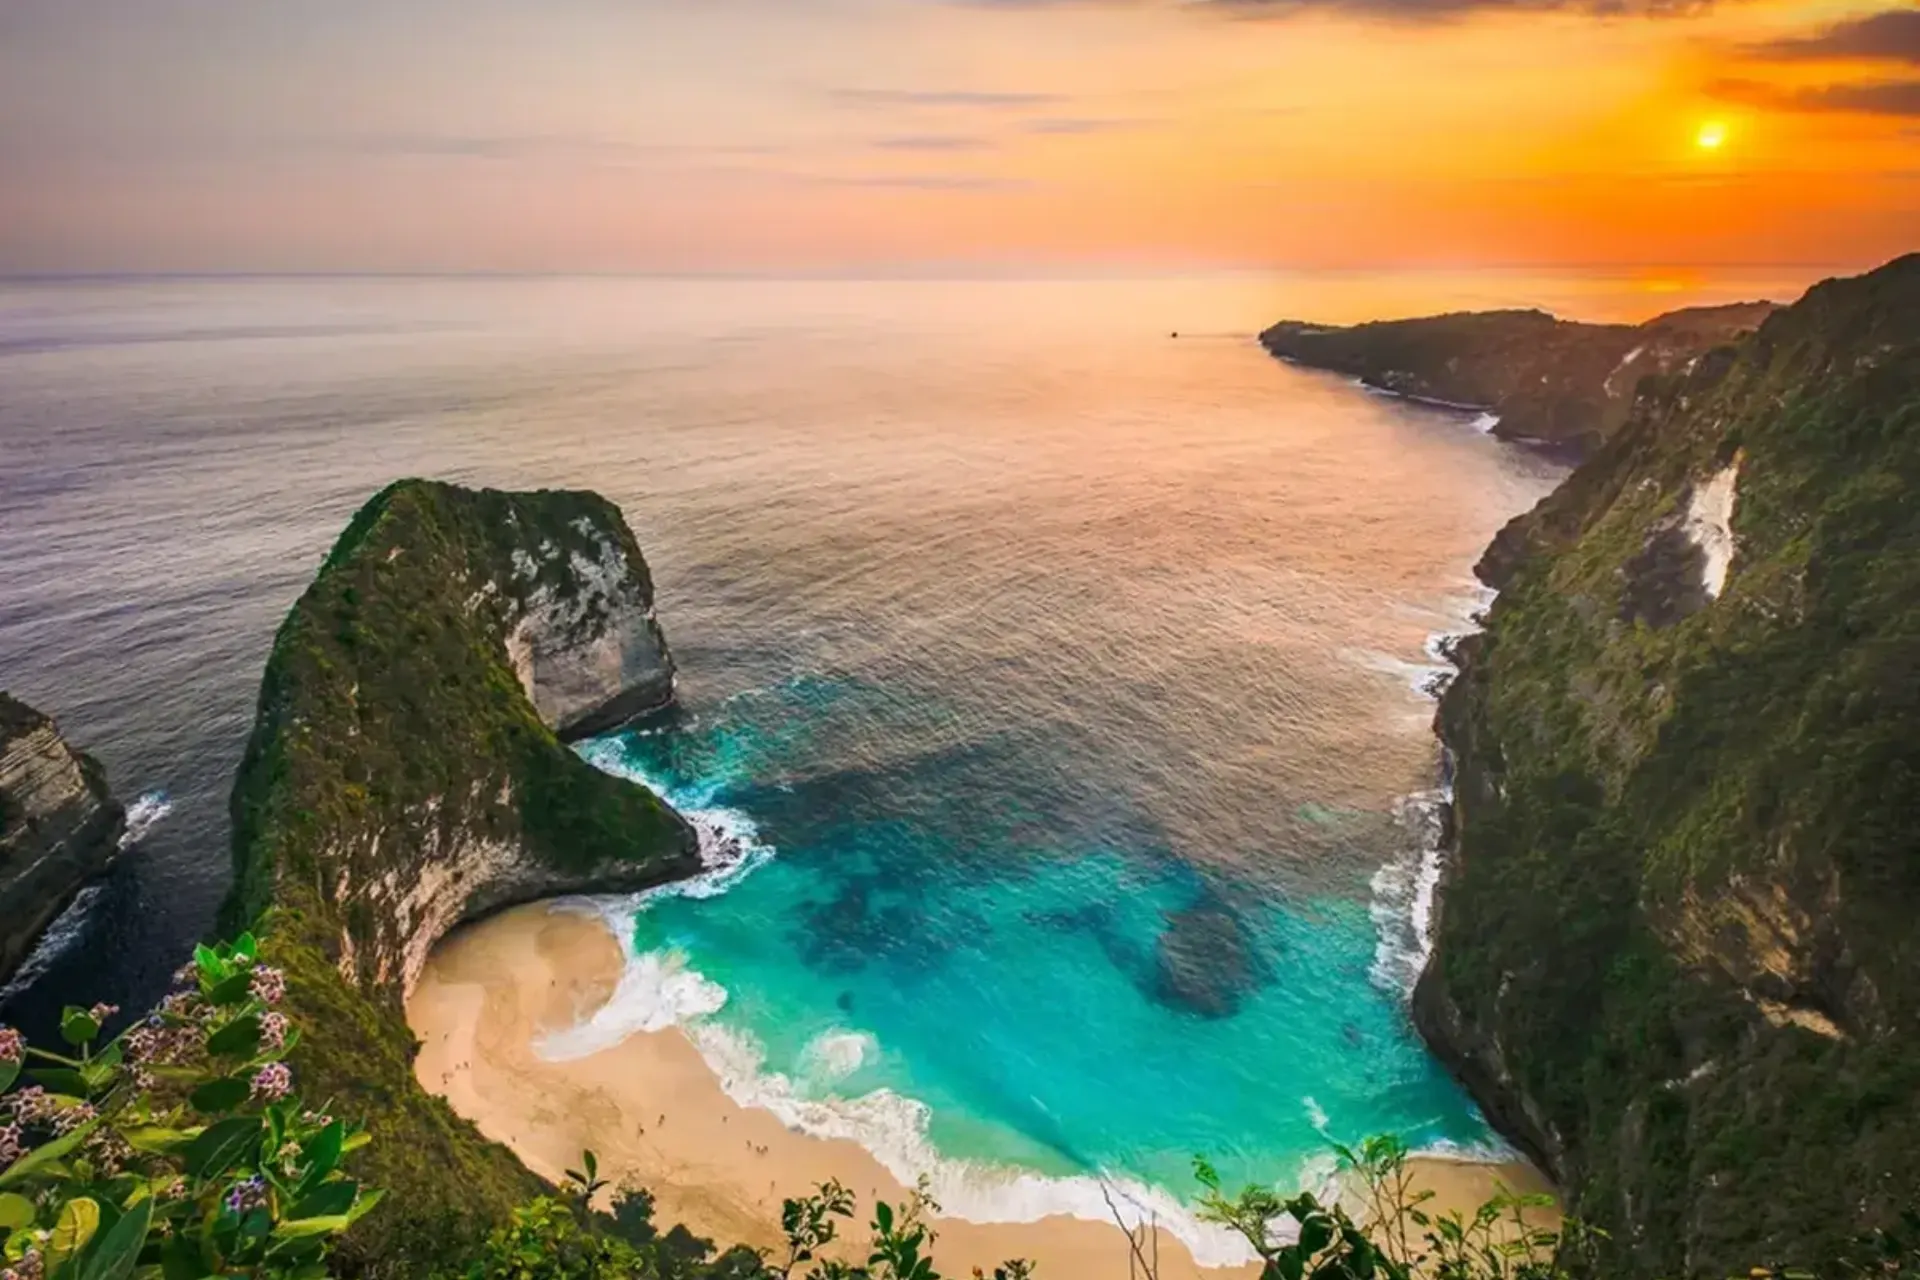
The famous T-Rex shaped cliff and pristine white sand beach below.
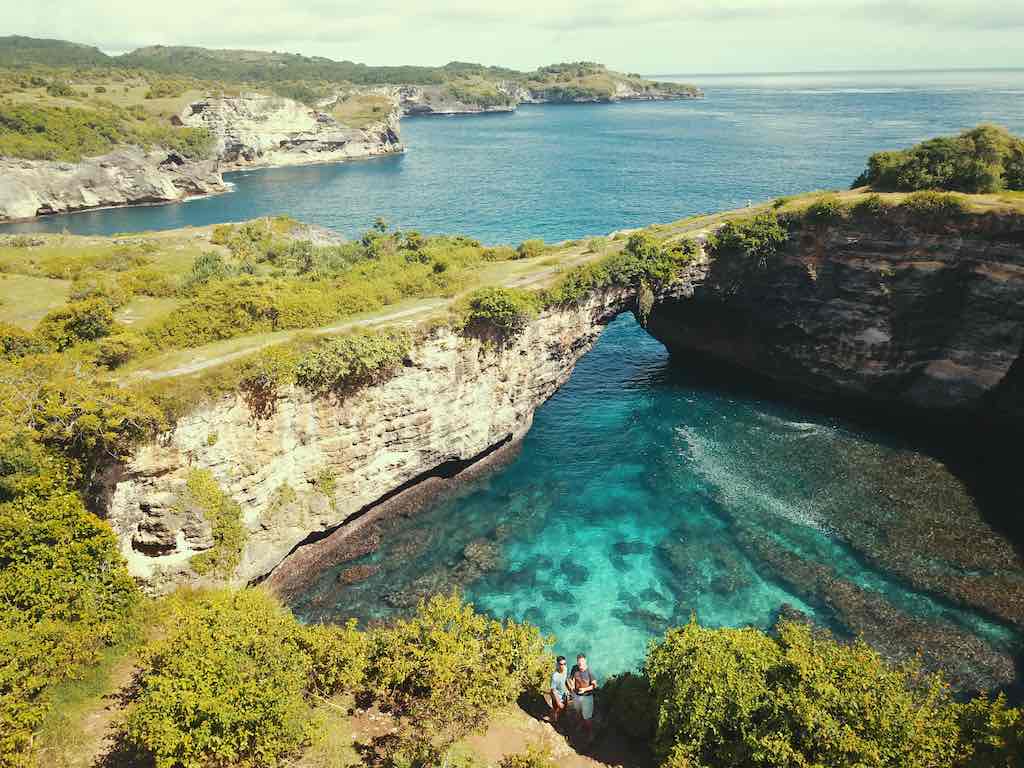
A scenic natural bridge arch over a turquoise sea cove.
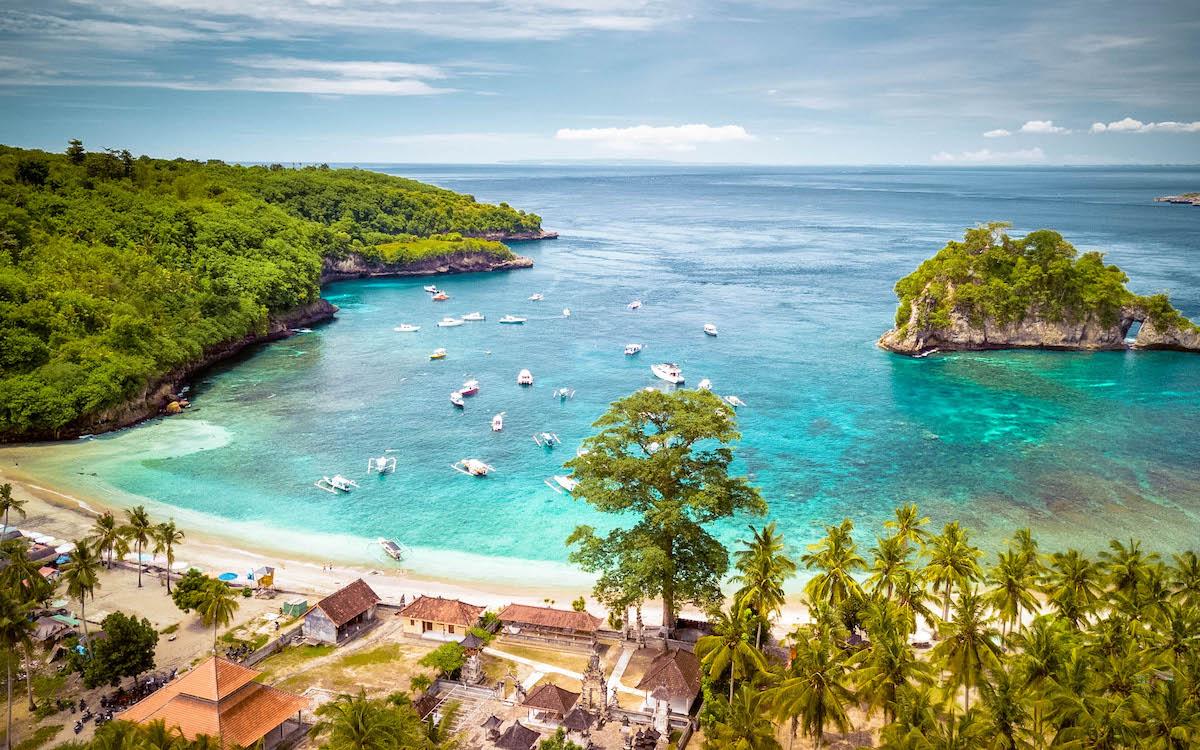
Famous palm-fringed beach offering spectacular Balinese sunsets and snorkeling.
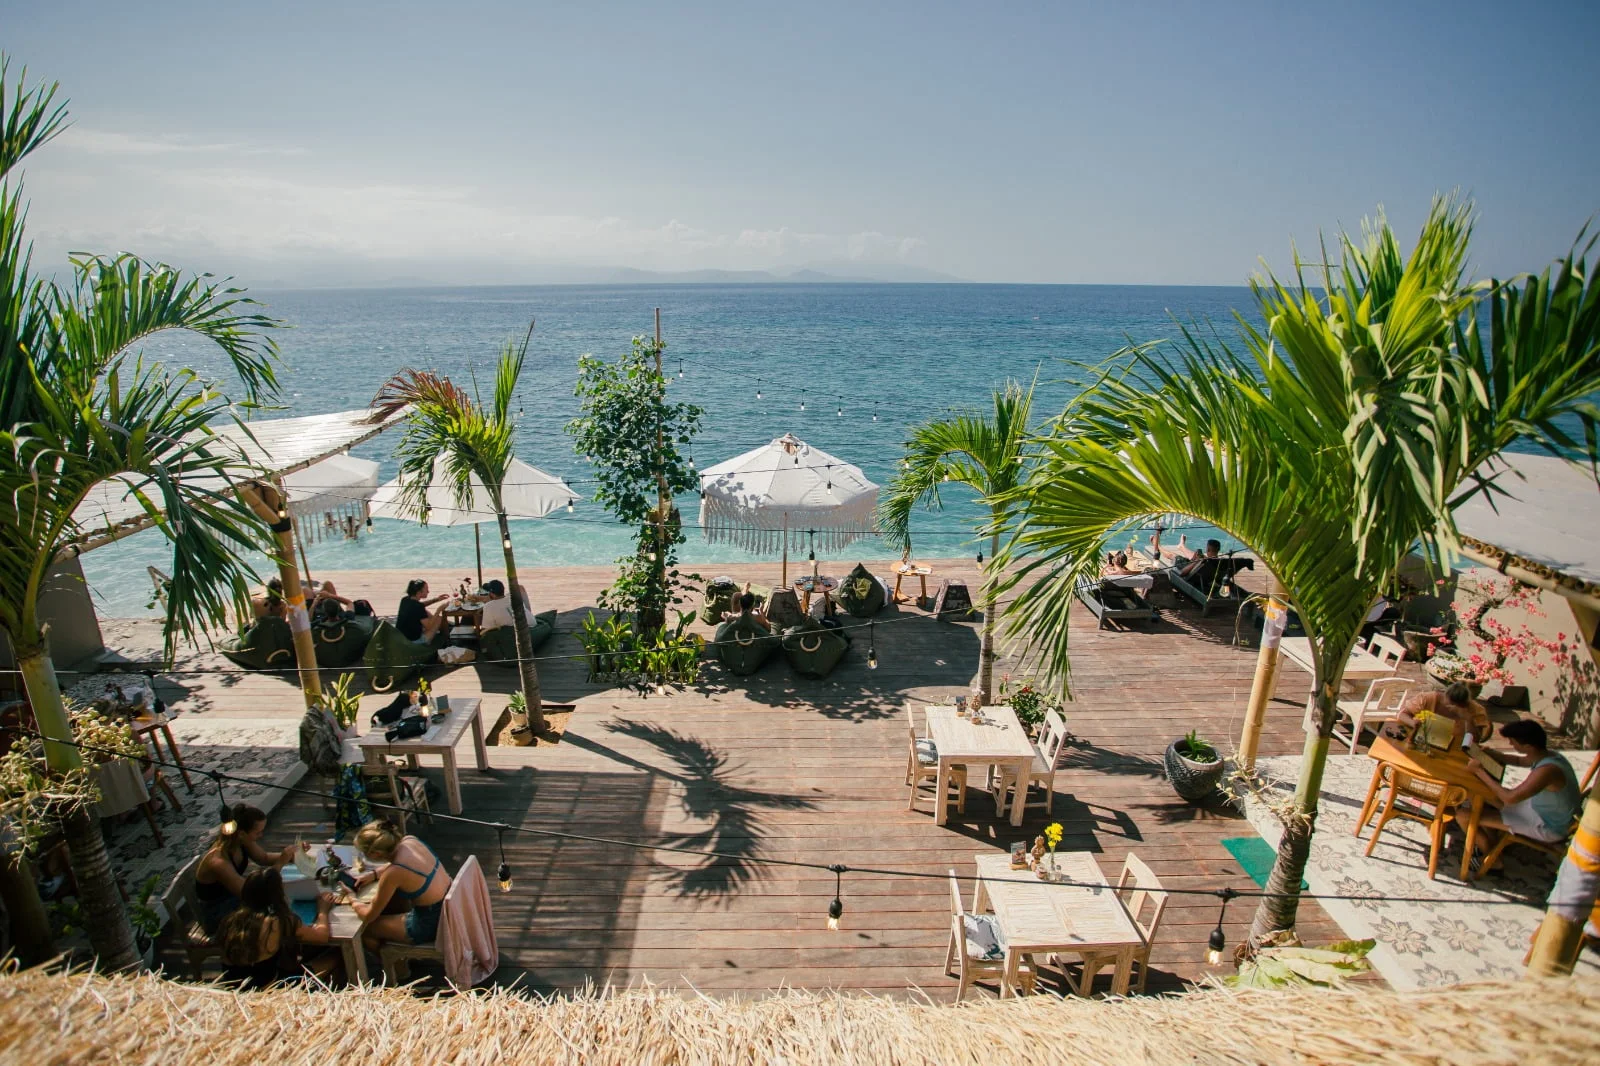
Famous beachside bar known for live music, sunset views, and signature cocktails.
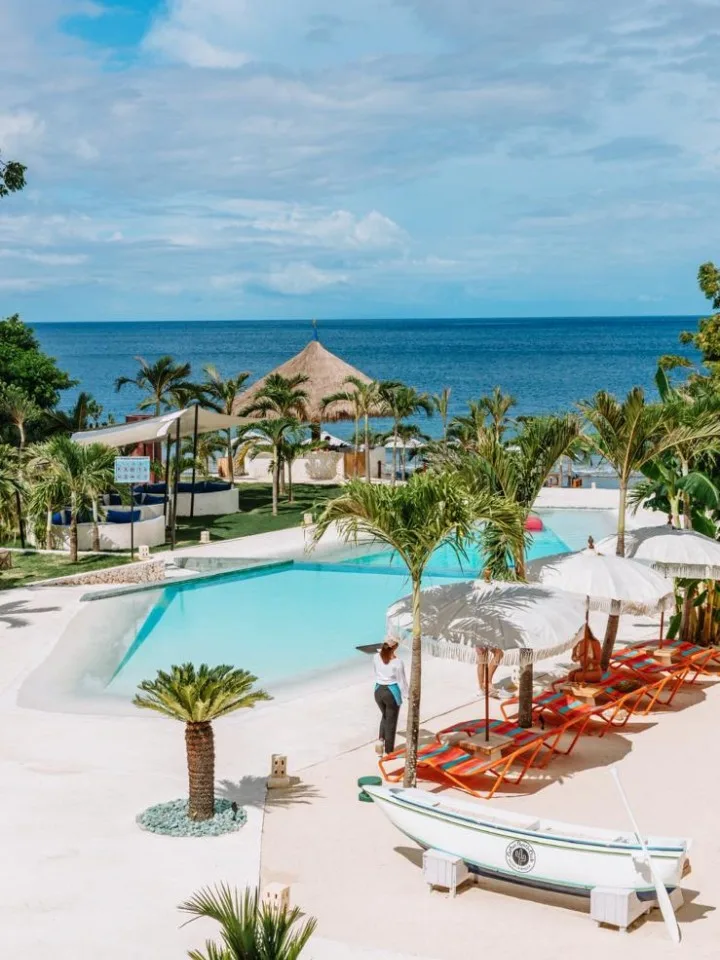
Popular day club featuring a large pool, relaxed atmosphere, and international DJ sets.
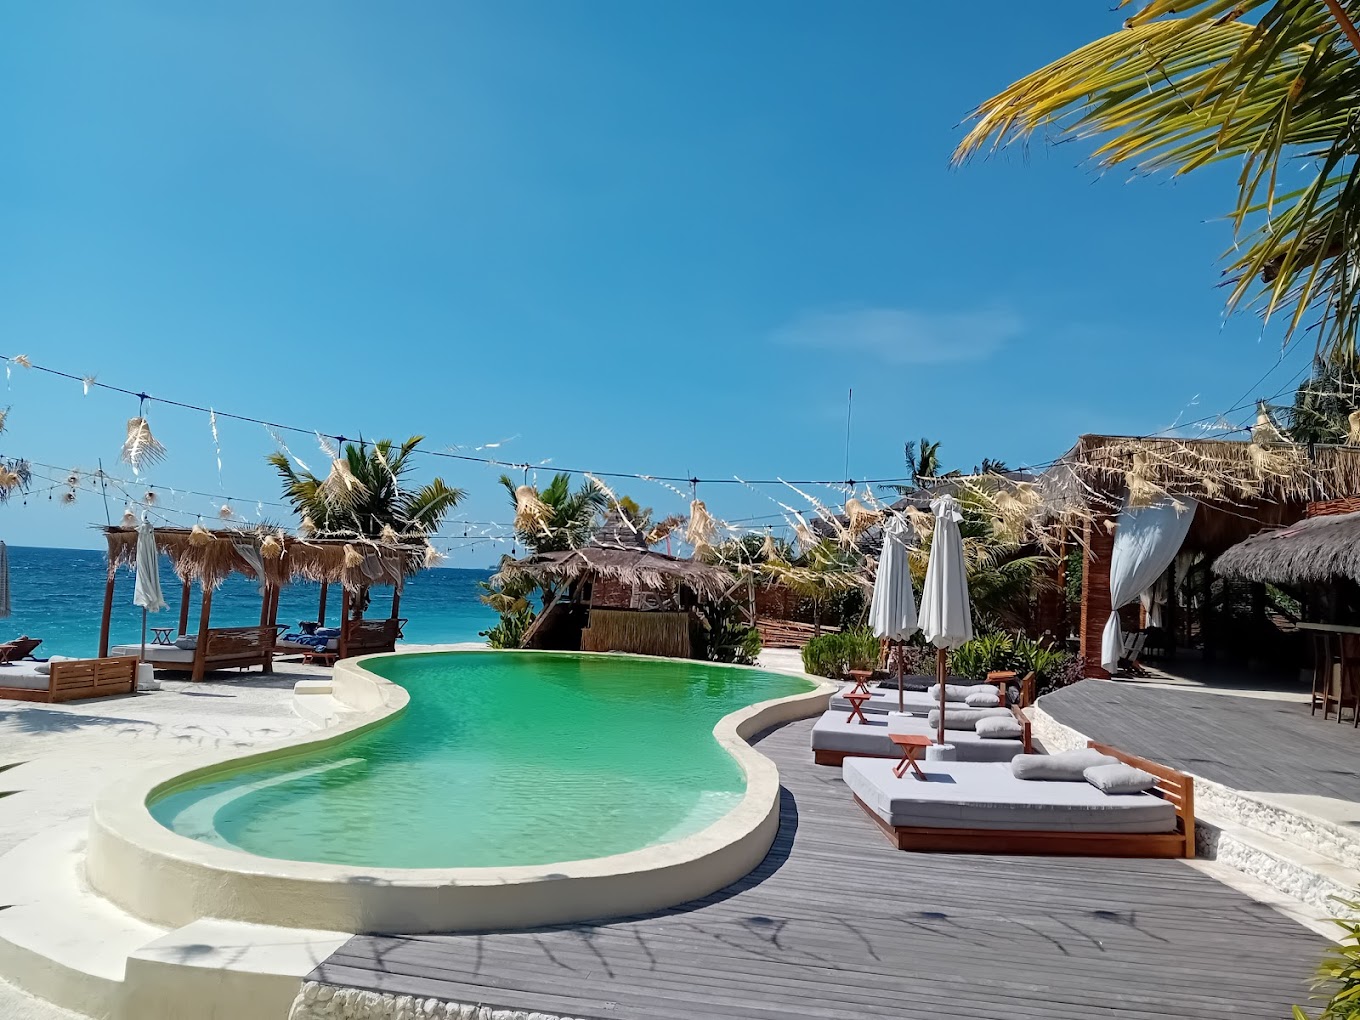
Premium beach club near Toyapakeh harbor with direct beach access and luxury daybeds.
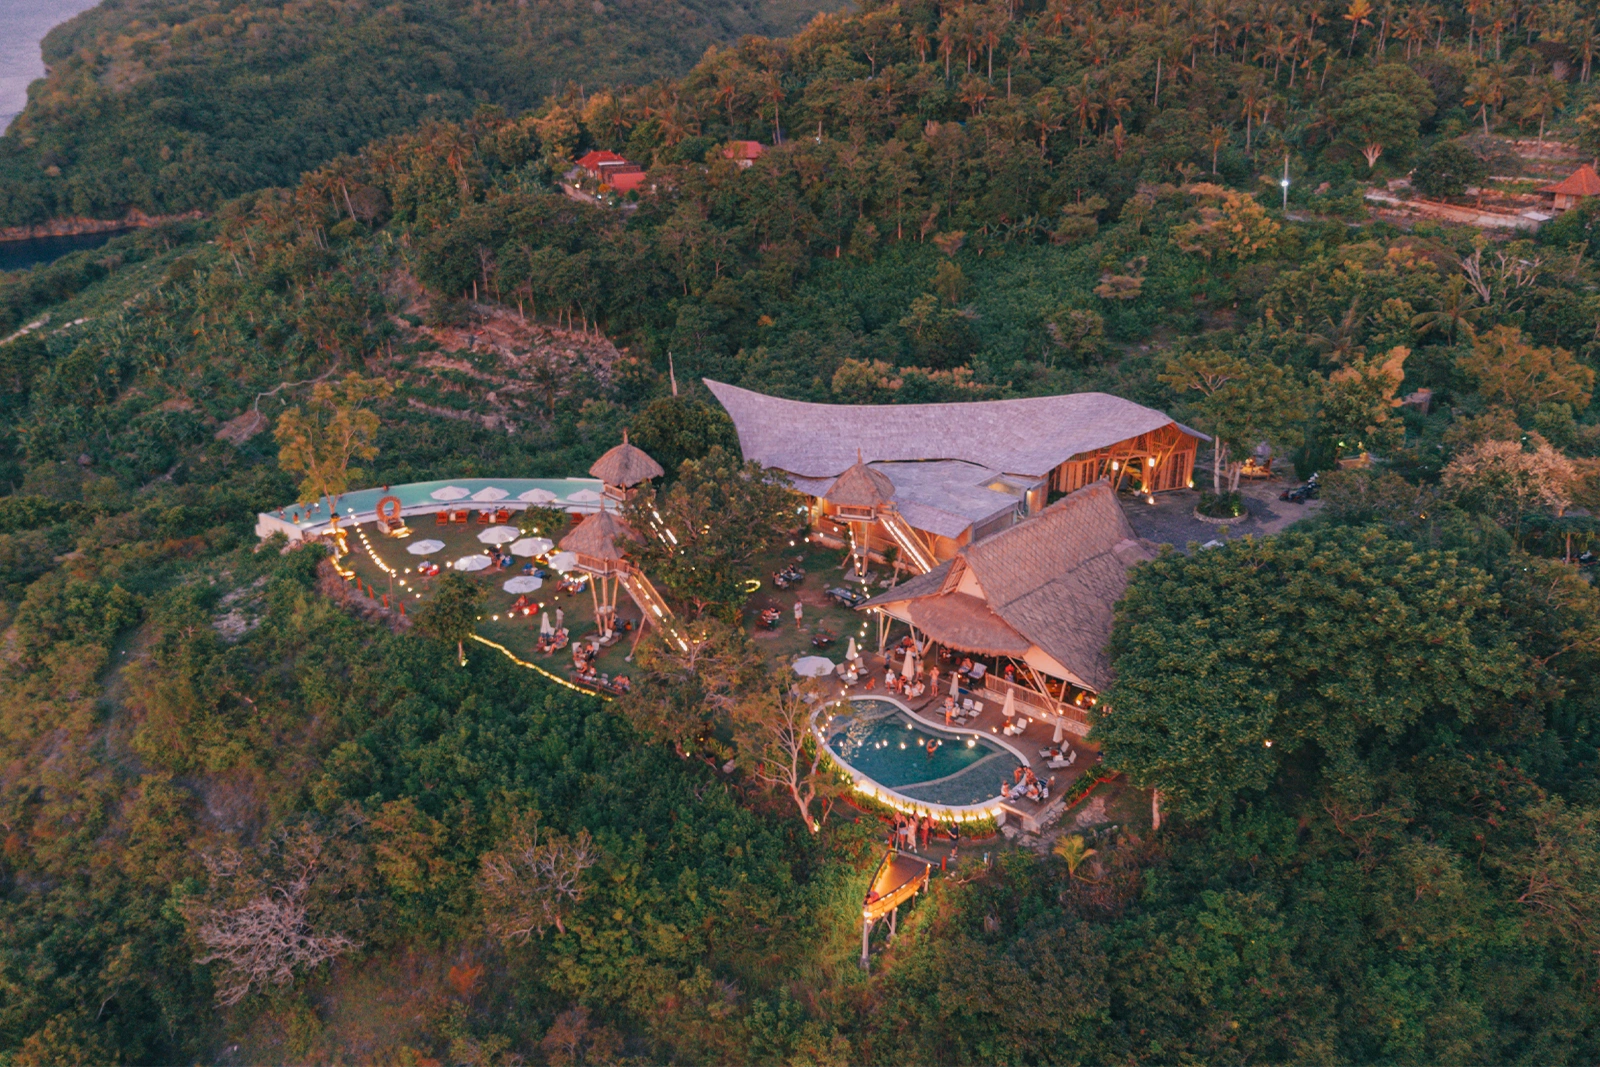
Iconic sunset destination offering panoramic ocean views and private bamboo nests.